Monday, August 10, 2026

Omega-3 Market Size, Share, Trends, and Growth Forecast - 2031

 The global Omega-3 Market is projected to reach USD 8.73 billion by 2031, registering a CAGR of 12.3% during the forecast period. The growth of the omega-3 market is driven by increasing consumer awareness regarding the health benefits of omega-3 fatty acids, particularly their role in cardiovascular, cognitive, and eye health. The growing demand for nutritional supplements, functional foods and beverages, infant nutrition, and pharmaceutical products is further contributing to market expansion.

Omega-3 fatty acids, particularly eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA), are essential fatty acids that the human body cannot efficiently synthesize. This has increased dependence on dietary sources and externally supplemented omega-3 ingredients. Manufacturers are increasingly incorporating omega-3 oils into capsules, powders, beverages, fortified foods, and other functional products while focusing on stability, bioavailability, and efficacy.

Fish oil, krill oil, and algal oil are among the most widely used sources of omega-3 fatty acids. Growing consumer preference for clean-label, sustainable, and naturally sourced ingredients is encouraging manufacturers to diversify their omega-3 portfolios. Increasing investments in algae-based omega-3 production and advancements in encapsulation technologies are also expected to create growth opportunities in the market.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=227

DHA Segment to Register the Fastest Growth During the Forecast Period

Based on type, the DHA segment is expected to register the fastest growth during the forecast period. DHA is a long-chain polyunsaturated omega-3 fatty acid that plays an important structural role in the brain and retina. Its significance in neurological and visual development has resulted in increasing demand for DHA across infant nutrition, dietary supplements, functional foods, and beverages.

DHA is naturally present in marine sources such as salmon and tuna, as well as in fish oils, dairy products, and specialty eggs. The growing body of research highlighting the importance of DHA for brain, eye, and cardiovascular health is increasing consumer awareness and supporting its incorporation into nutritional products.

The increasing use of DHA in infant formulas is another major factor contributing to the growth of this segment. DHA is particularly important during early life stages because of its role in brain and visual development. Rising demand for premium infant nutrition products, coupled with increasing consumer awareness about the importance of essential fatty acids, is expected to support the growth of the DHA segment.

Furthermore, the increasing availability of algal-derived DHA is expanding options for vegetarian and vegan consumers. This trend is particularly significant in developed markets, where demand for sustainable and plant-based nutritional ingredients is increasing.

Infant Formula Segment to Register the Highest CAGR During the Forecast Period

Based on application, the infant formula segment is expected to register the highest CAGR during the forecast period. The growth of this segment can be attributed primarily to increasing recognition of DHA as an important nutrient fr infant brain and eye development.

The increasing adoption of fortified infant formulas containing DHA and EPA is being supported by growing awareness among parents and healthcare professionals regarding early-life nutrition. Manufacturers are also developing premium infant formulas designed to replicate the nutritional composition of human breast milk, further supporting the use of omega-3 ingredients.

Regulatory developments in Europe have also contributed to the incorporation of DHA into infant and follow-on formulas. The European regulatory framework specifies DHA requirements for infant and follow-on formulas, creating consistent demand for DHA ingredients from manufacturers operating in the region.

In addition, rising demand for organic, clean-label, and nutritionally enhanced infant formulas is creating opportunities for omega-3 suppliers. Emerging economies are also expected to contribute to market growth as birth rates, household purchasing power, awareness of infant nutrition, and access to premium nutritional products increase.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=227

Europe to Account for a Significant Share of the Omega-3 Market

Europe is expected to account for a significant share of the global Omega-3 Market during the forecast period. The regional market is supported by high consumer awareness, stringent regulatory standards, growing demand for preventive healthcare, and strong adoption of dietary supplements and functional foods.

European consumers are increasingly seeking premium nutritional products containing recognizable and sustainably sourced ingredients. This trend is driving demand for fish oil as well as alternative sources such as algal-derived omega-3. The increasing vegetarian and flexitarian populations in countries such as Germany, the UK, and France are further supporting demand for algae-based omega-3 products.

The presence of established omega-3 manufacturers and ongoing investments in research and development are strengthening the European market. Companies are focusing on developing innovative formulations and expanding production capacities to meet the increasing demand for omega-3 ingredients across dietary supplements, functional foods and beverages, infant nutrition, and pharmaceutical applications.

Leading Omega-3 Companies:

The report profiles key players such as BASF SE (Germany), Cargill, Incorporated (US), DSM-Firmenich (Netherlands), ADM (US), Kerry Group plc (Ireland), Aker BioMarine (Norway), Croda International plc (UK), Corbion (Netherlands), Pelagia AS (Norway), KD Pharma Group SA (Switzerland), GC Rieber (Norway), Cooke Aquaculture Inc. (Canada), GOLDEN OMEGA (Chile), Polaris (France), Btsa (Spain), KinOmega Biopharm Inc. (China), Rimfrost AS (Norway), Mara Renewables (Canada), Cellana Inc. (US), and AlgaeCytes Limited (UK).

Controlled-release Fertilizers Market Growth: Key Drivers, Challenges, and Opportunities

 The global controlled-release fertilizers market is projected to grow from USD 2.69 billion in 2026 to USD 3.61 billion by 2031, registering a Compound Annual Growth Rate (CAGR) of 6.1% during the forecast period. The market is witnessing steady growth as farmers increasingly seek solutions that improve nutrient use efficiency, enhance crop productivity, and support sustainable agricultural practices.

The growing demand for higher crop yields and optimized nutrient management is a major factor driving the adoption of controlled-release fertilizers (CRFs). Unlike conventional fertilizers, CRFs are designed to provide nutrients gradually over an extended period, helping farmers maintain a consistent nutrient supply while reducing application frequency and nutrient losses.

Environmental concerns surrounding soil degradation, water contamination, nutrient runoff, and greenhouse gas emissions associated with conventional fertilizer use are further supporting market growth. Controlled-release solutions can minimize nutrient losses through leaching, volatilization, and runoff, making them an increasingly attractive option for sustainable agriculture.

Technological advancements are also transforming the CRFs landscape. Innovations in polymer-coated fertilizers, biodegradable coatings, multi-nutrient formulations, and advanced release technologies are improving fertilizer performance and expanding their applicability across different crops, soil conditions, and climatic environments. In addition, supportive government policies, increasing awareness of long-term cost savings, and the growing adoption of precision agriculture technologies are creating favorable conditions for market expansion.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=136099624

Nitrogen Stabilizers to Hold Significant Market Share

Based on type, the nitrogen stabilizers segment is estimated to account for a significant share of the global controlled-release fertilizers market. Nitrogen stabilizers play an important role in improving nutrient efficiency and reducing environmental losses. These products, including urease inhibitors and nitrification inhibitors, slow the conversion of nitrogen in the soil, allowing crops to absorb nutrients more effectively over an extended period.

By reducing nitrogen volatilization and leaching, nitrogen stabilizers can help maintain soil fertility, improve crop yields, and reduce the frequency of fertilizer applications. These benefits are particularly valuable for large-scale agricultural operations and high-value crops where efficient nutrient management is essential.

The increasing emphasis on sustainable farming and regulatory efforts to reduce nitrogen runoff are further encouraging the adoption of nitrogen-stabilized fertilizers. Leading companies, including ICL, Nutrien, SQM, and Yara, are incorporating nitrogen stabilizers into their fertilizer portfolios to address both agricultural productivity and environmental sustainability requirements.

As farmers become more aware of the benefits associated with improved nitrogen utilization, nitrogen-stabilized fertilizers are expected to maintain a substantial position within the controlled-release fertilizers market.

Time-release Systems to Dominate by Function

Based on function, time-release systems are expected to hold the largest share of the controlled-release fertilizers market. Time-release systems are designed to provide a consistent supply of nutrients over an extended period, helping synchronize nutrient availability with crop uptake. Polymer-coated and matrix-based formulations can minimize nutrient losses caused by leaching, volatilization, and runoff while supporting efficient crop nutrition.

The widespread application of time-release fertilizers across cereals, vegetables, fruits, horticultural crops, and high-value plantations highlights their versatility. Farmers are increasingly adopting these systems because they can reduce fertilizer application frequency, lower labor requirements, and generate long-term operational cost benefits.

The growing focus on sustainable nutrient management is also contributing to the segment's growth. Continued innovation in biodegradable coatings, controlled-release mechanisms, and multi-nutrient formulations is expected to strengthen the position of time-release systems in the market.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=136099624

North America to Account for the Largest Market Share

By region, North America is estimated to account for the largest share of the global controlled-release fertilizers market.

The region's strong position is supported by its developed agricultural infrastructure, extensive farmland, and widespread adoption of advanced crop management technologies. Farmers across North America are increasingly focused on improving nutrient efficiency and crop yields while reducing the environmental impact associated with fertilizer use.

Controlled-release fertilizers are gaining traction across row crops, horticulture, and high-value agricultural applications due to their ability to provide more efficient nutrient delivery. The presence of major industry participants, including ICL, Nutrien, Yara, and SQM, along with established manufacturing and distribution networks, further supports market development in the region.

Technological developments in polymer-coated fertilizers, multi-nutrient CRFs, and biodegradable coating technologies are enabling manufacturers to address diverse crop, soil, and climatic requirements. Government initiatives promoting sustainable agriculture and precision farming are also creating a favorable environment for controlled-release fertilizer adoption.

Leading Controlled-release Fertilizers Companies:

The report profiles key players such as Yara (Norway), Nutrien Ltd. (Canada), Mosaic (US), ICL (Israel), Nufarm (Australia), Kingenta (China), ScottsMiracle-Gro (US), Koch Industries (US), Helena Chemicals (US), SQM (Chile), Haifa Negev Technologies Ltd. (Israel), JCAM AGRI Co., Ltd. (Japan), COMPO EXPERT (Germany), The Andersons Inc. (US), and Van Iperen International (Netherlands).

Tuesday, August 4, 2026

Vitamin K2 Market Analysis: Opportunities and Future Outlook

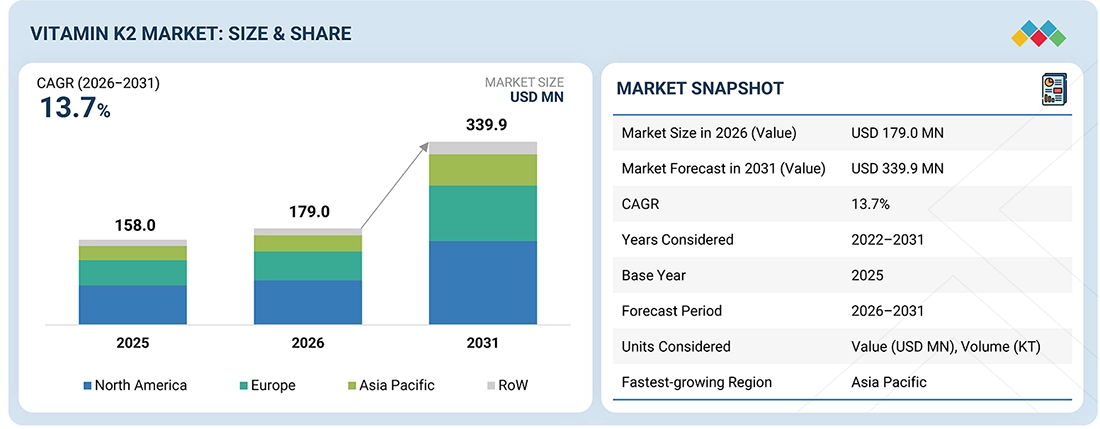
The global Vitamin K2 market is projected to grow from USD 179.0 million in 2026 to USD 339.9 million by 2031, registering a CAGR of 13.7% during the forecast period. The market is witnessing robust growth as consumers increasingly recognize the role of Vitamin K2 in supporting bone strength, cardiovascular health, and healthy calcium metabolism. As preventive healthcare, healthy aging, and functional nutrition continue to gain traction worldwide, Vitamin K2 is emerging as a key ingredient in dietary supplements, pharmaceuticals, and fortified food and beverage products.


Vitamin K2 plays a unique role in activating proteins that direct calcium to bones and teeth while preventing calcium buildup in soft tissues. This scientifically supported benefit has increased its adoption across multiple product formats, including capsules, tablets, soft gels, powders, gummies, and functional foods. The growing popularity of combination formulations containing Vitamin D3, calcium, and Vitamin K2 is further contributing to market expansion. In addition, consumer demand for clean-label, non-GMO, and clinically validated nutritional ingredients is expected to accelerate market growth over the coming years.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=80962397

Natural Source Segment Expected to Register the Fastest Growth

Based on source, the natural segment is projected to record the highest growth rate throughout the forecast period. Naturally derived Vitamin K2, primarily produced through bacterial fermentation, offers superior bioavailability and aligns with the increasing consumer preference for plant-based, sustainable, and naturally sourced nutritional ingredients.

The growing use of natural Vitamin K2 in dietary supplements, functional foods, and pharmaceutical formulations has encouraged manufacturers to invest in advanced fermentation technologies that improve product quality, purity, and production capacity. Furthermore, supportive regulatory developments and rising consumer confidence in naturally derived ingredients are expected to strengthen the segment's growth prospects.

Pharmaceuticals Application to Witness the Highest CAGR

By application, the pharmaceuticals segment is anticipated to register the fastest CAGR during the forecast period. A growing body of clinical evidence highlighting the benefits of Vitamin K2 in bone mineralization, osteoporosis management, cardiovascular health, and vascular calcification prevention is encouraging wider adoption across medical and therapeutic applications.

Healthcare professionals are increasingly recommending Vitamin K2 in combination with Vitamin D3 and calcium to improve bone density and reduce fracture risk, particularly among aging populations. Pharmaceutical manufacturers are also expanding their portfolios with prescription and medically formulated Vitamin K2 products as research continues to validate its therapeutic potential. Rising osteoporosis cases, Vitamin K deficiencies in specific patient populations, and greater emphasis on preventive healthcare are expected to further drive demand for pharmaceutical-grade Vitamin K2.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=80962397

Asia Pacific Emerges as the Fastest-Growing Regional Market

The Asia Pacific region is projected to be the fastest-growing market for Vitamin K2 during the forecast period. Growth is being driven by favorable demographic trends, increasing healthcare expenditure, expanding nutritional awareness, and rising adoption of preventive healthcare practices.

Countries including Japan, China, and South Korea are witnessing rapid growth in their aging populations, resulting in increased prevalence of osteoporosis and cardiovascular disorders. This demographic transition is generating significant demand for nutritional ingredients that support bone health and reduce arterial calcification risks. Rising disposable incomes, expanding dietary supplement consumption, and growing awareness of healthy aging solutions are expected to further strengthen the regional market outlook.

Leading Vitamin K2 Companies

The report profiles several leading participants operating in the global Vitamin K2 market, including Gnosis by Lesaffre (France), Balchem Corp (US), J-OIL MILLS, INC (Japan), Novonesis A/S (Denmark), Guangdong Sungen Bioscience Co., Ltd. (China), Vesta Nutra (US), Menadiona (Spain), GF Fermentech (South Korea), AngelYeast Co., Ltd. (China), and GeneFerm Biotechnology Co., Ltd. (Taiwan).

The increasing demand for clinically supported nutritional ingredients, combined with innovations in fermentation technology, expanding pharmaceutical applications, and growing consumer preference for preventive wellness solutions, is expected to position the Vitamin K2 market for sustained growth through 2031.

Specialty Fertilizers Market Report: Key Drivers, Challenges, and Competitive Landscape

 The global specialty fertilizer market is projected to grow from USD 32.29 billion in 2026 to USD 45.49 billion by 2031, registering a CAGR of 7.1% during the forecast period.

The global specialty fertilizer market is poised for robust growth as agricultural producers increasingly adopt advanced crop nutrition solutions to improve productivity, optimize nutrient-use efficiency, and support sustainable farming practices. The growing demand for high-quality agricultural output, coupled with advancements in precision agriculture and modern irrigation technologies, continues to accelerate market expansion across developed and emerging economies.

Specialty fertilizers—including controlled-release fertilizers, water-soluble fertilizers, micronutrients, and fertigation products—are becoming integral components of modern farming systems. Farmers, agribusinesses, and commercial growers are increasingly utilizing these solutions to maximize crop yields while minimizing nutrient losses and environmental impact.

The rising awareness of balanced plant nutrition, increasing recognition of soil nutrient deficiencies, and expanding implementation of data-driven nutrient management practices are strengthening demand across major agricultural regions, particularly Asia Pacific, North America, and Europe. In addition, supportive government initiatives, expanding distribution networks, greenhouse cultivation, and continued investments in sustainable agriculture are creating favorable conditions for market growth worldwide.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=57479139

Micronutrients Segment Maintains Strong Market Position

Based on technology, the micronutrients segment continues to account for a significant share of the specialty fertilizer market. As intensive farming practices and continuous cropping reduce essential nutrients in agricultural soils, growers are increasingly incorporating micronutrient fertilizers into their crop nutrition programs.

Essential nutrients such as zinc, iron, boron, manganese, copper, and molybdenum play vital roles in photosynthesis, enzyme activation, and nutrient metabolism, directly influencing crop productivity and quality. Demand is particularly strong in fruits, vegetables, oilseeds, pulses, and horticultural crops, where micronutrient deficiencies can significantly affect both yield and market value.

The increasing availability of chelated micronutrient formulations, wider adoption of foliar applications and fertigation systems, and growing awareness of balanced fertilization practices are further supporting segment growth. Government-led soil health initiatives and nutrient management programs continue to encourage farmers to adopt micronutrient-based specialty fertilizers.

Fruits & Vegetables Segment Expected to Register Strong Growth

By crop type, the fruits & vegetables segment is projected to witness significant growth throughout the forecast period. Rising global consumption of fresh produce and increasing demand for premium-quality fruits and vegetables are encouraging growers to invest in advanced fertilizer technologies that enhance crop performance.

Specialty fertilizers enable precise nutrient delivery throughout the crop growth cycle, helping improve fruit size, color, nutritional value, shelf life, and overall quality while reducing nutrient wastage. Water-soluble fertilizers, controlled-release fertilizers, micronutrients, and fertigation products have become essential tools for high-value horticultural production.

The expansion of greenhouse cultivation, protected agriculture, and export-oriented horticulture—particularly across Asia Pacific, Europe, and North America—is expected to further strengthen demand for specialty fertilizers in this segment.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=57479139

Europe Emerges as a Key Regional Market

Europe represents one of the leading regional markets for specialty fertilizers, supported by advanced farming practices, stringent environmental regulations, and widespread adoption of precision nutrient management technologies.

Farmers across Germany, France, Italy, Spain, and the United Kingdom are increasingly utilizing water-soluble fertilizers, controlled-release fertilizers, and micronutrient products to enhance crop productivity while improving fertilizer-use efficiency and reducing environmental impact.

The region's emphasis on sustainable agriculture, soil health improvement, greenhouse cultivation, and production of high-value crops continues to drive adoption of innovative specialty fertilizer solutions across cereals, fruits, vegetables, horticultural crops, and specialty crop applications. Continued investments in agricultural innovation and precision farming technologies are expected to reinforce Europe's leadership position in the global specialty fertilizer market over the coming years.

Leading Specialty Fertilizers Companies:

The specialty fertilizer market features a competitive landscape with the presence of several global and regional manufacturers focused on innovation, product development, strategic partnerships, and sustainable agricultural solutions. Key market participants include Nutrien Ltd. (Canada), Yara International ASA (Norway), ICL Group Ltd. (Israel), K+S Aktiengesellschaft (Germany), SQM S.A. (Chile), EuroChem Group (Switzerland), CF Industries Holdings, Inc. (US), Nufarm Limited (Australia), The Mosaic Company (US), OCI Global (Netherlands), OCP Group (Morocco), Kingenta Ecological Engineering Group Co., Ltd. (China), Coromandel International Limited (India), Deepak Fertilisers and Petrochemicals Corporation Limited (India), Zuari Agro Chemicals Limited (India), Kugler Company (US), Haifa Group (Israel), COMPO EXPERT GmbH (Germany), Wilbur-Ellis Holdings, Inc. (US), Valagro S.p.A. (Italy), BRANDT, Inc. (US), and AgroLiquid (US).

As global agriculture increasingly prioritizes sustainability, resource efficiency, and precision crop management, specialty fertilizers are expected to play an increasingly critical role in supporting higher agricultural productivity and long-term food security. Continued technological innovation, favorable government policies, and growing awareness of balanced crop nutrition are anticipated to drive sustained market growth through 2031.